Key takeaways
- Bank Negara held the OPR at 2.75% in September 2026, the same level since July 2025.
- In our example, a 4.8% gross yield falls to about 3.6% after maintenance, sinking fund, assessment and one empty month.
- Malaysians pay no RPGT after five years of ownership; sell within three years and it is 30% of the gain.
- Foreign buyers in KL need to spend at least RM1 million and pay a flat 8% stamp duty from 2026.
In the worked example below, an RM700,000 condo near an MRT station looks like a 4.8% gross yield on paper. After running costs and one empty month it is about 3.6%. Add a loan and the rent falls roughly RM8,100 a year short of the instalments.
So is KL property a good investment in 2026? Yes, for the right property, bought at the right price and held long enough. This guide shows how to test a unit before you book, the costs investors usually miss and a worked example with real numbers.
You will also find practical tips for foreign and local buyers near the end.
What makes a KL unit worth investing in?
You will hear two stories about KL: that condos only go up, and that the city is full of empty serviced apartments. Both are partly right, so the real question is not whether KL is a good investment, but whether this unit, at this price, is a good investment for you.
The basics have not changed. Look for a short, real walk to an MRT or LRT station, mature amenities, steady tenant demand and an entry price that makes sense against recent transactions in the same building.
Decide first whether you want rental income, capital growth or a mix. That choice drives the area, the unit size and the layout, because a compact unit near a station and a family three-bedroom home attract very different tenants.
Then look at competing supply. According to NAPIC data for the first half of 2026, reported by The Edge, Malaysia had 23,375 completed but unsold serviced apartments worth RM19.33 billion, and over 55% were priced between RM500,001 and RM1 million. Check how many similar units in and around your building are listed for rent before you assume a yield.
Which numbers should you check first?
Before you fall for the show unit, check these six things.
- Price per sq ft: compare with recent transacted prices in the same building or street, not with launch prices
- Rent: find out what similar units actually let for, not what owners are asking
- Holding costs: maintenance fee, sinking fund (10% of the maintenance charge for strata units), assessment and quit rent
- Financing: your loan margin and interest rate decide your monthly cash flow
- Exit: how many units in the building sell each year, and at what price
- Timeline: an off-plan unit completing in 2030 ties up money for years before any rent comes in
What does the 2026 backdrop look like?
Borrowing costs are steady. Bank Negara kept the OPR at 2.75% at its September 2026 meeting, the level it has held since July 2025, and an economist quoted by the NST expects it to stay there at the November meeting.
Short-term rental rules are also being written. The housing ministry told Parliament on 26 October 2026 that a national framework is in final review, that operators in strata buildings stay bound by their JMB or MC by-laws, and that no nationwide cap on nights has been announced, according to EdgeProp.
What does a well-located investment unit look like?
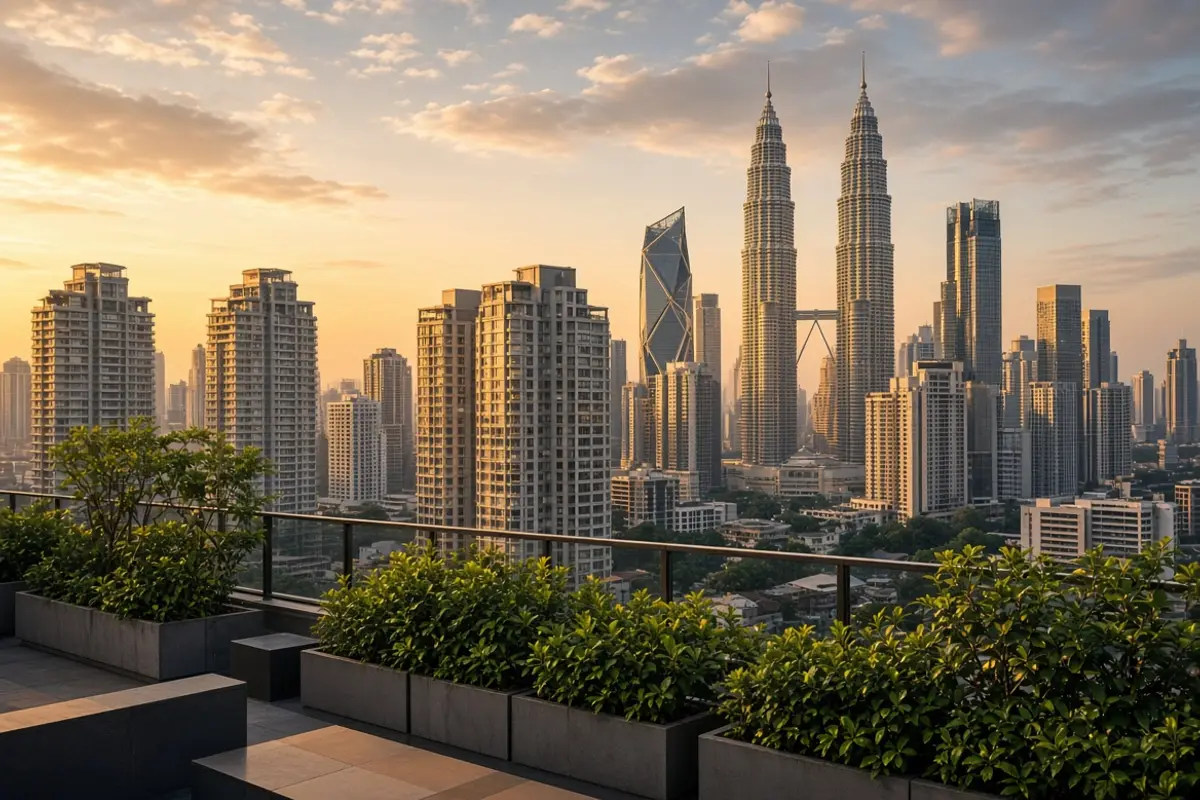
KL360 on Jalan Raja Uda shows the profile many investors look for. It is a freehold serviced residence by GD Properties in a 61-storey tower, about 50 metres from Raja Uda MRT station on the Putrajaya Line, with completion listed for 2030.
According to EdgeProp, its 785 serviced apartments come in 25 layouts from 450 to 920 sq ft, sizes that suit the rental market near the city centre. Because handover is several years away, it fits buyers who can carry progressive payments through construction, not someone who needs rent next year.
Foreign buyers: in Kuala Lumpur the minimum price for foreigners is RM1 million, so only units priced at that level or above are open to them. From 1 January 2026, foreigners also pay a flat 8% stamp duty on residential transfers.
Which costs do investors underestimate?
The purchase price gets all the attention. These costs tend to get missed.
- Stamp duty and legal fees on the purchase, which raise your true entry price
- Progressive payments and loan interest during construction, before any rent arrives
- Furnishing, repairs and agent fees each time a tenant changes
- Empty months between tenants
- Weak building management or an ageing block, which can push up repairs and put tenants off
- Real property gains tax if you sell early: for Malaysians, 30% of the gain within three years, 20% in year four, 15% in year five and nothing after that
- Income tax on net rent, at your normal rate if you are a Malaysian tax resident
Foreign buyers: non-citizens pay real property gains tax (RPGT) of 30% on a sale within five years and 10% after that, so there is no tax-free point as there is for citizens and permanent residents.
What it looks like in real numbers
Say you buy an 800 sq ft condo near an MRT station for RM700,000 and let it for RM2,800 a month. All figures are illustrations, not a forecast.
- Gross rent: RM2,800 x 12 = RM33,600 a year, a 4.8% gross yield
- Maintenance at RM0.40 per sq ft: RM320 a month, or RM3,840 a year
- Sinking fund at 10% of maintenance: RM384 a year
- Assessment and quit rent: say RM1,200 a year
- One empty month: RM2,800
- Net rent: RM33,600 minus RM8,224 = RM25,376, about a 3.6% net yield
Now add a loan. Borrow 90% (RM630,000) over 35 years at an assumed 4% a year and the instalment is about RM2,790 a month, or roughly RM33,470 a year. Your net rent leaves you about RM8,100 short each year, roughly RM675 a month, although part of every instalment is paying down the loan.
Stamp duty on the transfer adds RM15,000 at the start for a Malaysian buyer: 1% on the first RM100,000, 2% on the next RM400,000 and 3% on the last RM200,000. From there, your return depends on long-term price growth, which is why location and entry price matter so much.
What are the best tips for investing in Kuala Lumpur property?
Run through these before you book, whether you are a foreign or a local buyer.
- 1Work out net yield, not gross. Deduct maintenance, sinking fund, assessment, quit rent and empty months before comparing with your loan rate, because brochure yields are usually gross.
- 2Check price per sq ft against recent sales. Compare with transacted prices in the same building or street, not launch prices.
- 3Count the competing units. Check how many similar units in and around the building are already listed for rent before you assume a yield.
- 4Test your cash flow with the loan. In our example, net rent fell about RM8,100 a year short of the instalments, so run your own loan offer before you book.
- 5Budget for the costs that bite. Add stamp duty and legal fees to your entry price, then allow for furnishing, repairs, agent fees and empty months between tenants.
- 6Plan to hold beyond five years. Malaysian citizens and permanent residents pay no RPGT after year five. Non-citizens pay 30% within five years and 10% after that.
- 7Know your buyer rules. Foreigners pay a flat 8% stamp duty from 1 January 2026 and need a RM1 million minimum price in Kuala Lumpur. Malaysians pay tiered rates (RM15,000 in our example).
Bottom line
KL can still be a sound long-term investment in 2026, but the numbers rarely work on rent alone. Buy for location and a fair entry price, plan to hold beyond five years, when RPGT drops to zero for Malaysians, and budget for every holding cost.
Next step: pick two or three units you like and run each one through the example above with real rents, real fees and your own loan offer.
Frequently asked questions
What is a good rental yield in Kuala Lumpur?
There is no single figure. Work out the net yield after maintenance, sinking fund, assessment, quit rent and empty months, then compare it with your loan rate. Brochure yields are usually gross figures, so they look higher than what owners actually keep.
Is a new launch or subsale better for investment in KL?
A subsale unit lets you check real rents and condition and start earning sooner. A new launch spreads payments over construction but delays income and carries completion risk. Compare the price per sq ft of both in the same area before deciding.
Can foreigners buy property in Kuala Lumpur?
Yes, with state consent and a minimum price of RM1 million. Foreigners cannot buy Malay Reserved Land, low-cost or Bumiputera quota units, and from 1 January 2026 they pay a flat 8% stamp duty on residential transfers.
When can I sell property without paying RPGT?
Malaysian citizens and permanent residents pay no RPGT on disposals after the fifth year of ownership. Non-citizens pay 30% within five years and 10% after that.
What are your top tips for investing in KL property?
Work out net yield after maintenance, sinking fund, assessment, quit rent and empty months. Compare price per sq ft with recent sales and test your cash flow with your real loan offer. Hold beyond five years if you can. Foreign buyers should check the RM1 million Kuala Lumpur minimum and the flat 8% stamp duty.
Related Project
KL360
A destination-driven freehold service residence beside Raja Uda MRT — home to Malaysia's first 360° immersive sky deck, glass sky walk and infinity pool with city skyline views.
View Project